Home Loan Documents Checklist 2026: Complete List for Salaried and Self-Employed
Introduction
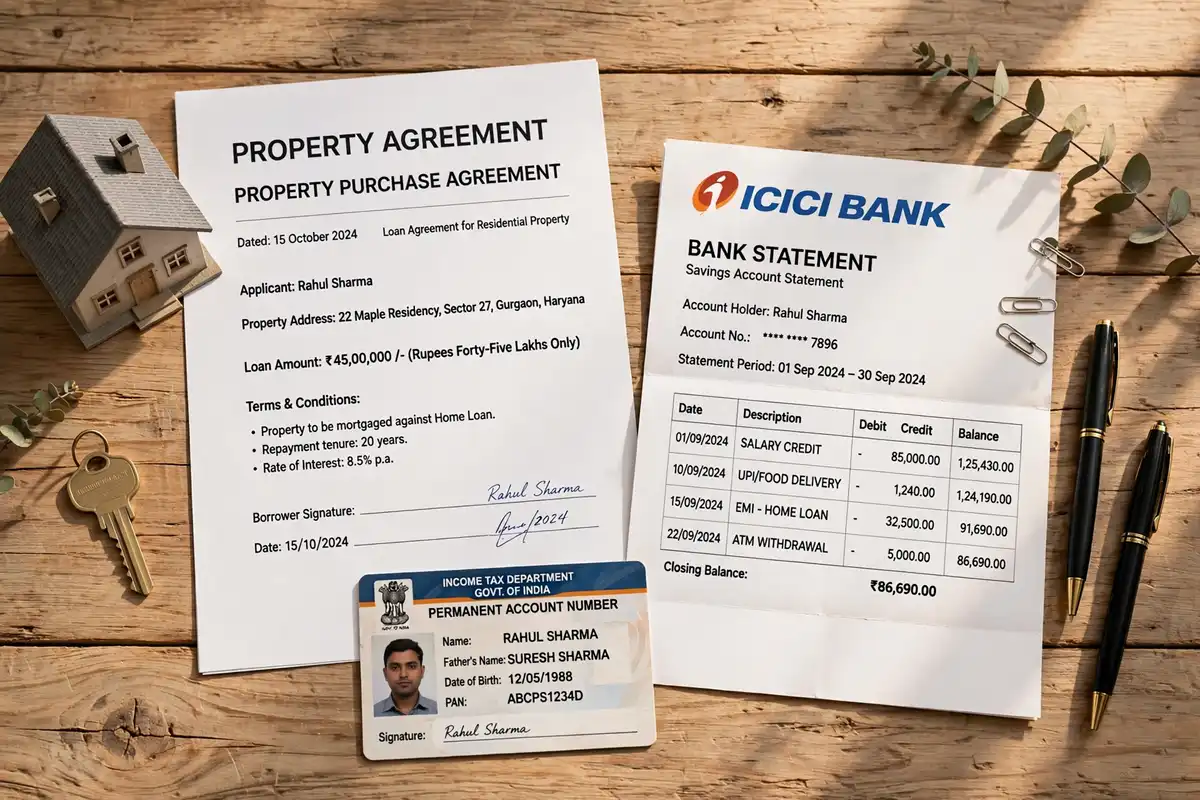
Applying for a home loan in India means submitting a stack of documents that prove who you are, what you earn, and that the property you are buying is legally clean. Banks typically ask for identity and address proof, income proof for the last 6 to 12 months, bank statements, and the full set of property papers — and missing even one document can delay your approval by days or weeks. For salaried applicants the list is shorter; for self-employed applicants it is longer, because the bank must verify business income through tax returns and financial statements. This guide gives you the complete home loan documents checklist for 2026, separately for salaried and self-employed borrowers, so you can keep everything ready before you apply and get your loan sanctioned faster.
Key Takeaways
- Every home loan applicant needs identity proof, address proof, income proof, bank statements and property documents — keep scanned copies ready before applying.
- Salaried applicants usually need salary slips for the last 3 to 6 months, Form 16 for the last 2 years and bank statements for the last 6 months.
- Self-employed applicants need income tax returns for the last 2 to 3 years, audited financial statements, business proof and bank statements for the last 12 months.
- Property documents include the sale agreement, title deed, approved building plan, occupancy certificate and the seller’s chain of ownership papers.
- Missing or mismatched documents — different names, old addresses or unsigned papers — are among the most common reasons for home loan delays and rejections.
- Keeping a single digital folder with clear, readable scans of every document can cut your approval time from weeks to a few days.
Home Loan Documents Checklist at a Glance
The table below summarises everything most banks and housing finance companies ask for. The exact list varies slightly by lender, but if you keep these documents ready, you will rarely be asked for anything extra.
| Document category | What you need | Who it applies to |
|---|---|---|
| Identity proof | PAN card (mandatory), Aadhaar card, passport, voter ID or driving licence | All applicants and co-applicants |
| Address proof | Aadhaar, passport, utility bill, rent agreement or voter ID | All applicants |
| Income proof (salaried) | Salary slips (3–6 months), Form 16 (2 years), appointment letter | Salaried applicants |
| Income proof (self-employed) | ITR (2–3 years), audited P&L and balance sheet, GST returns | Self-employed applicants |
| Bank statements | Last 6 months (salaried) or 12 months (self-employed) | All applicants |
| Employment/business proof | Employment certificate or business registration, licence, GST certificate | All applicants |
| Property documents | Sale agreement, title deed, approved plan, OC, EC, NOCs | All applicants |
| Photographs | Passport-size photographs of all applicants | All applicants |
Identity and Address Proof
Your PAN card is mandatory for a home loan in India — no lender will process an application without it. Along with PAN, you will need one more government-issued photo ID such as an Aadhaar card, passport, voter ID or driving licence. Banks use these to complete your KYC and to check your identity against credit bureau records, so the name and date of birth on every document must match exactly. Even a small spelling difference between your PAN and your Aadhaar can trigger a query and stall your file.
For address proof, lenders usually accept your Aadhaar card, passport, voter ID, a recent utility bill (electricity, gas or post-paid mobile bill not older than 3 months), or a registered rent agreement. If you live at a different address from the one on your ID, carry proof of your current address separately. If you are applying with a co-applicant — your spouse, parent or sibling — the same identity and address documents are needed for them too, and their income documents are also collected if their income is being considered.
Income Proof for Salaried Applicants
For salaried borrowers, the bank’s main question is simple: is your income stable, and can you afford the EMI? To answer it, lenders ask for your salary slips for the last 3 to 6 months, Form 16 for the last 2 years, and your bank statement for the last 6 months showing salary credits. They check that the salary credited to your account matches the amount on your slips, and that your job is stable — most banks prefer applicants with at least 2 years of work experience and 6 months to 1 year with the current employer.
You will also need an employment certificate or appointment letter from your employer, and some banks ask for your employee ID card or a letter confirming your designation and date of joining. If you earn variable pay such as bonuses or incentives, keep the last 2 years’ Form 16 handy, because banks usually count only a part of variable income when calculating your loan eligibility. Keep your salary account statement clean: frequent cheque bounces or large unexplained cash deposits in the months before applying can raise questions.
Income Proof for Self-Employed Applicants
Self-employed borrowers face a longer checklist because the bank cannot rely on a salary slip. Lenders usually ask for your income tax returns for the last 2 to 3 years, along with the computation of income, your audited profit and loss statement and balance sheet for the last 2 to 3 years, and your business bank statements for the last 12 months. They look for stable or growing profits, because your eligibility is calculated on your average declared income, not on your turnover.
You will also need proof that your business exists and is active: your business registration certificate, GST registration and GST returns, trade licence, or partnership deed or memorandum of association for firms and companies. Professionals such as doctors, chartered accountants and architects may need to submit their practice licence or degree certificate. If your business is new — less than 2 to 3 years old — many banks will ask for a longer track record or a co-applicant with a stable income, and some lenders may offer a lower loan amount. Keep your business and personal bank accounts separate and your tax filings up to date; a clean, consistent ITR history is the single biggest factor in a self-employed home loan approval.
Salaried vs Self-Employed: Document Comparison
| Document | Salaried | Self-employed |
|---|---|---|
| Income tax returns | Usually not asked, Form 16 is enough | Last 2–3 years, mandatory |
| Salary slips | Last 3–6 months | Not applicable |
| Form 16 | Last 2 years | Not applicable |
| Audited financials | Not needed | P&L and balance sheet, last 2–3 years |
| Bank statements | Last 6 months | Last 12 months |
| Employment/business proof | Appointment letter, employer certificate | Registration, GST certificate, licence |
| Typical processing time | 5–10 working days | 10–20 working days |
Property Documents You Must Collect
The property documents matter as much as your income papers, because the bank lends against the property itself. For a property you are buying from a builder, you need the sale agreement or allotment letter, the approved building plan, the commencement certificate, the occupancy certificate (or completion certificate for a ready property), the builder’s title documents, and the no-objection certificates from the relevant authorities. For a resale property, you also need the original title deed, the chain of previous sale deeds going back 13 to 30 years, the encumbrance certificate for the last 13 to 30 years, the latest property tax receipts, and the society’s share certificate and NOC if the flat is in a housing society.
The bank will carry out its own legal and technical verification of the property, but it is your responsibility to make sure the papers are in order before you sign the agreement. Check that the seller’s name on the title deed matches the name in the sale agreement, that the property is not mortgaged or under litigation, and that the approved plan matches the actual construction. Any mismatch — an extra room not in the plan, a missing occupancy certificate, or a disputed title — can delay or even block the loan, and in a worst case leave you with a property the bank will not finance.
Additional Documents in Special Cases
Some situations need extra paperwork. If you are buying jointly, the co-applicant’s full KYC and income documents are required. NRIs applying for a home loan need a valid passport and visa, an overseas address proof, an NRE or NRO account statement, a power of attorney if someone in India is signing on their behalf, and an employment contract or salary certificate from their foreign employer. If you are taking a loan against a property you already own, or applying for a balance transfer, the bank will ask for the original property papers, the existing loan sanction letter and a statement of the outstanding balance from your current lender.
Pensioners applying for a home loan should keep their pension payment order and pension account statements ready. If you have any existing loans, keep their sanction letters and latest statements handy, because the bank will factor those EMIs into your eligibility. And if your home loan involves a gift or family funds for the down payment, some banks ask for a gift deed and proof of the source of those funds.
How to Keep Your Documents Ready: A 5-Step Plan
1. Create one digital folder
Scan or photograph every document in clear, readable colour and save them in a single folder on your phone or computer, with file names such as “PAN-card.pdf” and “salary-slip-Oct-2026.pdf”. Banks now accept scanned copies for the first stage, and you will only need originals for final verification.
2. Match names and dates across documents
Check that your name, date of birth and address are identical on your PAN, Aadhaar, passport, salary slips and bank statements. Fix mismatches with the issuing authority before you apply, not after.
3. Keep 6 to 12 months of statements ready
Download your bank statements from net banking rather than visiting a branch, and make sure they show your salary credits or business receipts clearly. Keep the last 2 years of Form 16 or ITRs in the same folder.
4. Ask the seller or builder for property papers early
Request the complete property document set — title deed, approved plan, occupancy certificate and encumbrance certificate — before you pay the booking amount. Review them yourself or get a lawyer to check them.
5. Keep originals safe and accessible
When the bank asks for original documents for verification, carry them in a file and take them back the same day. Never hand over originals to anyone other than the bank’s authorised officer, and keep a note of what you submitted and when.
Common Document Mistakes That Delay Home Loans
The most common delay is submitting documents with mismatched names or old addresses — for example, an Aadhaar card that still shows your previous city. Blurred or cropped scans are another frequent cause of rejection at the first stage; banks will simply return the file and ask you to resubmit. Applicants also forget to include all pages of their bank statements or submit statements from a different account than the one where their salary is credited. Self-employed applicants often submit ITRs without the computation of income or unaudited financials, which the bank cannot accept. And many buyers sign the sale agreement before collecting the property’s title and approval papers, only to discover later that a document is missing and the loan cannot be disbursed until it is produced.
Frequently Asked Questions
Is a PAN card mandatory for a home loan?
Yes. A PAN card is mandatory for every applicant and co-applicant. Banks also need it to check your credit history with bureaus like CIBIL, so you cannot get a home loan without one.
How many months of bank statements are needed for a home loan?
Salaried applicants usually need bank statements for the last 6 months. Self-employed applicants are generally asked for the last 12 months of business account statements, and sometimes personal account statements too.
Can I get a home loan without Form 16?
Form 16 is the standard income proof for salaried applicants, but if you do not have it, most banks will accept your income tax returns for the last 2 years along with salary slips and bank statements showing salary credits.
What property documents does the bank check before approving a home loan?
The bank checks the sale agreement, the title deed and chain of ownership, the approved building plan, the occupancy or completion certificate, the encumbrance certificate, property tax receipts, and NOCs from the society or authorities. It also carries out its own legal and technical verification.
Do self-employed people need more documents for a home loan?
Yes. Self-employed applicants must submit income tax returns for the last 2 to 3 years, audited profit and loss statements and balance sheets, GST returns, business registration proof and 12 months of bank statements. Processing usually takes longer than for salaried applicants.
Can I apply for a home loan if my Aadhaar address is different from my current address?
Yes, but you must submit a separate proof of your current address, such as a rent agreement or a recent utility bill. Banks verify your current address separately, and some may do a physical verification visit.
How long does home loan approval take once documents are submitted?
If all documents are complete and correct, salaried applicants usually get approval in 5 to 10 working days, while self-employed applicants may take 10 to 20 working days because of the extra income verification. Disbursement happens after the property’s legal and technical checks are complete.
Disclaimer: Document requirements vary by lender and are based on publicly available information in 2026. Always confirm the exact checklist with your bank or housing finance company before applying.

Post Comment